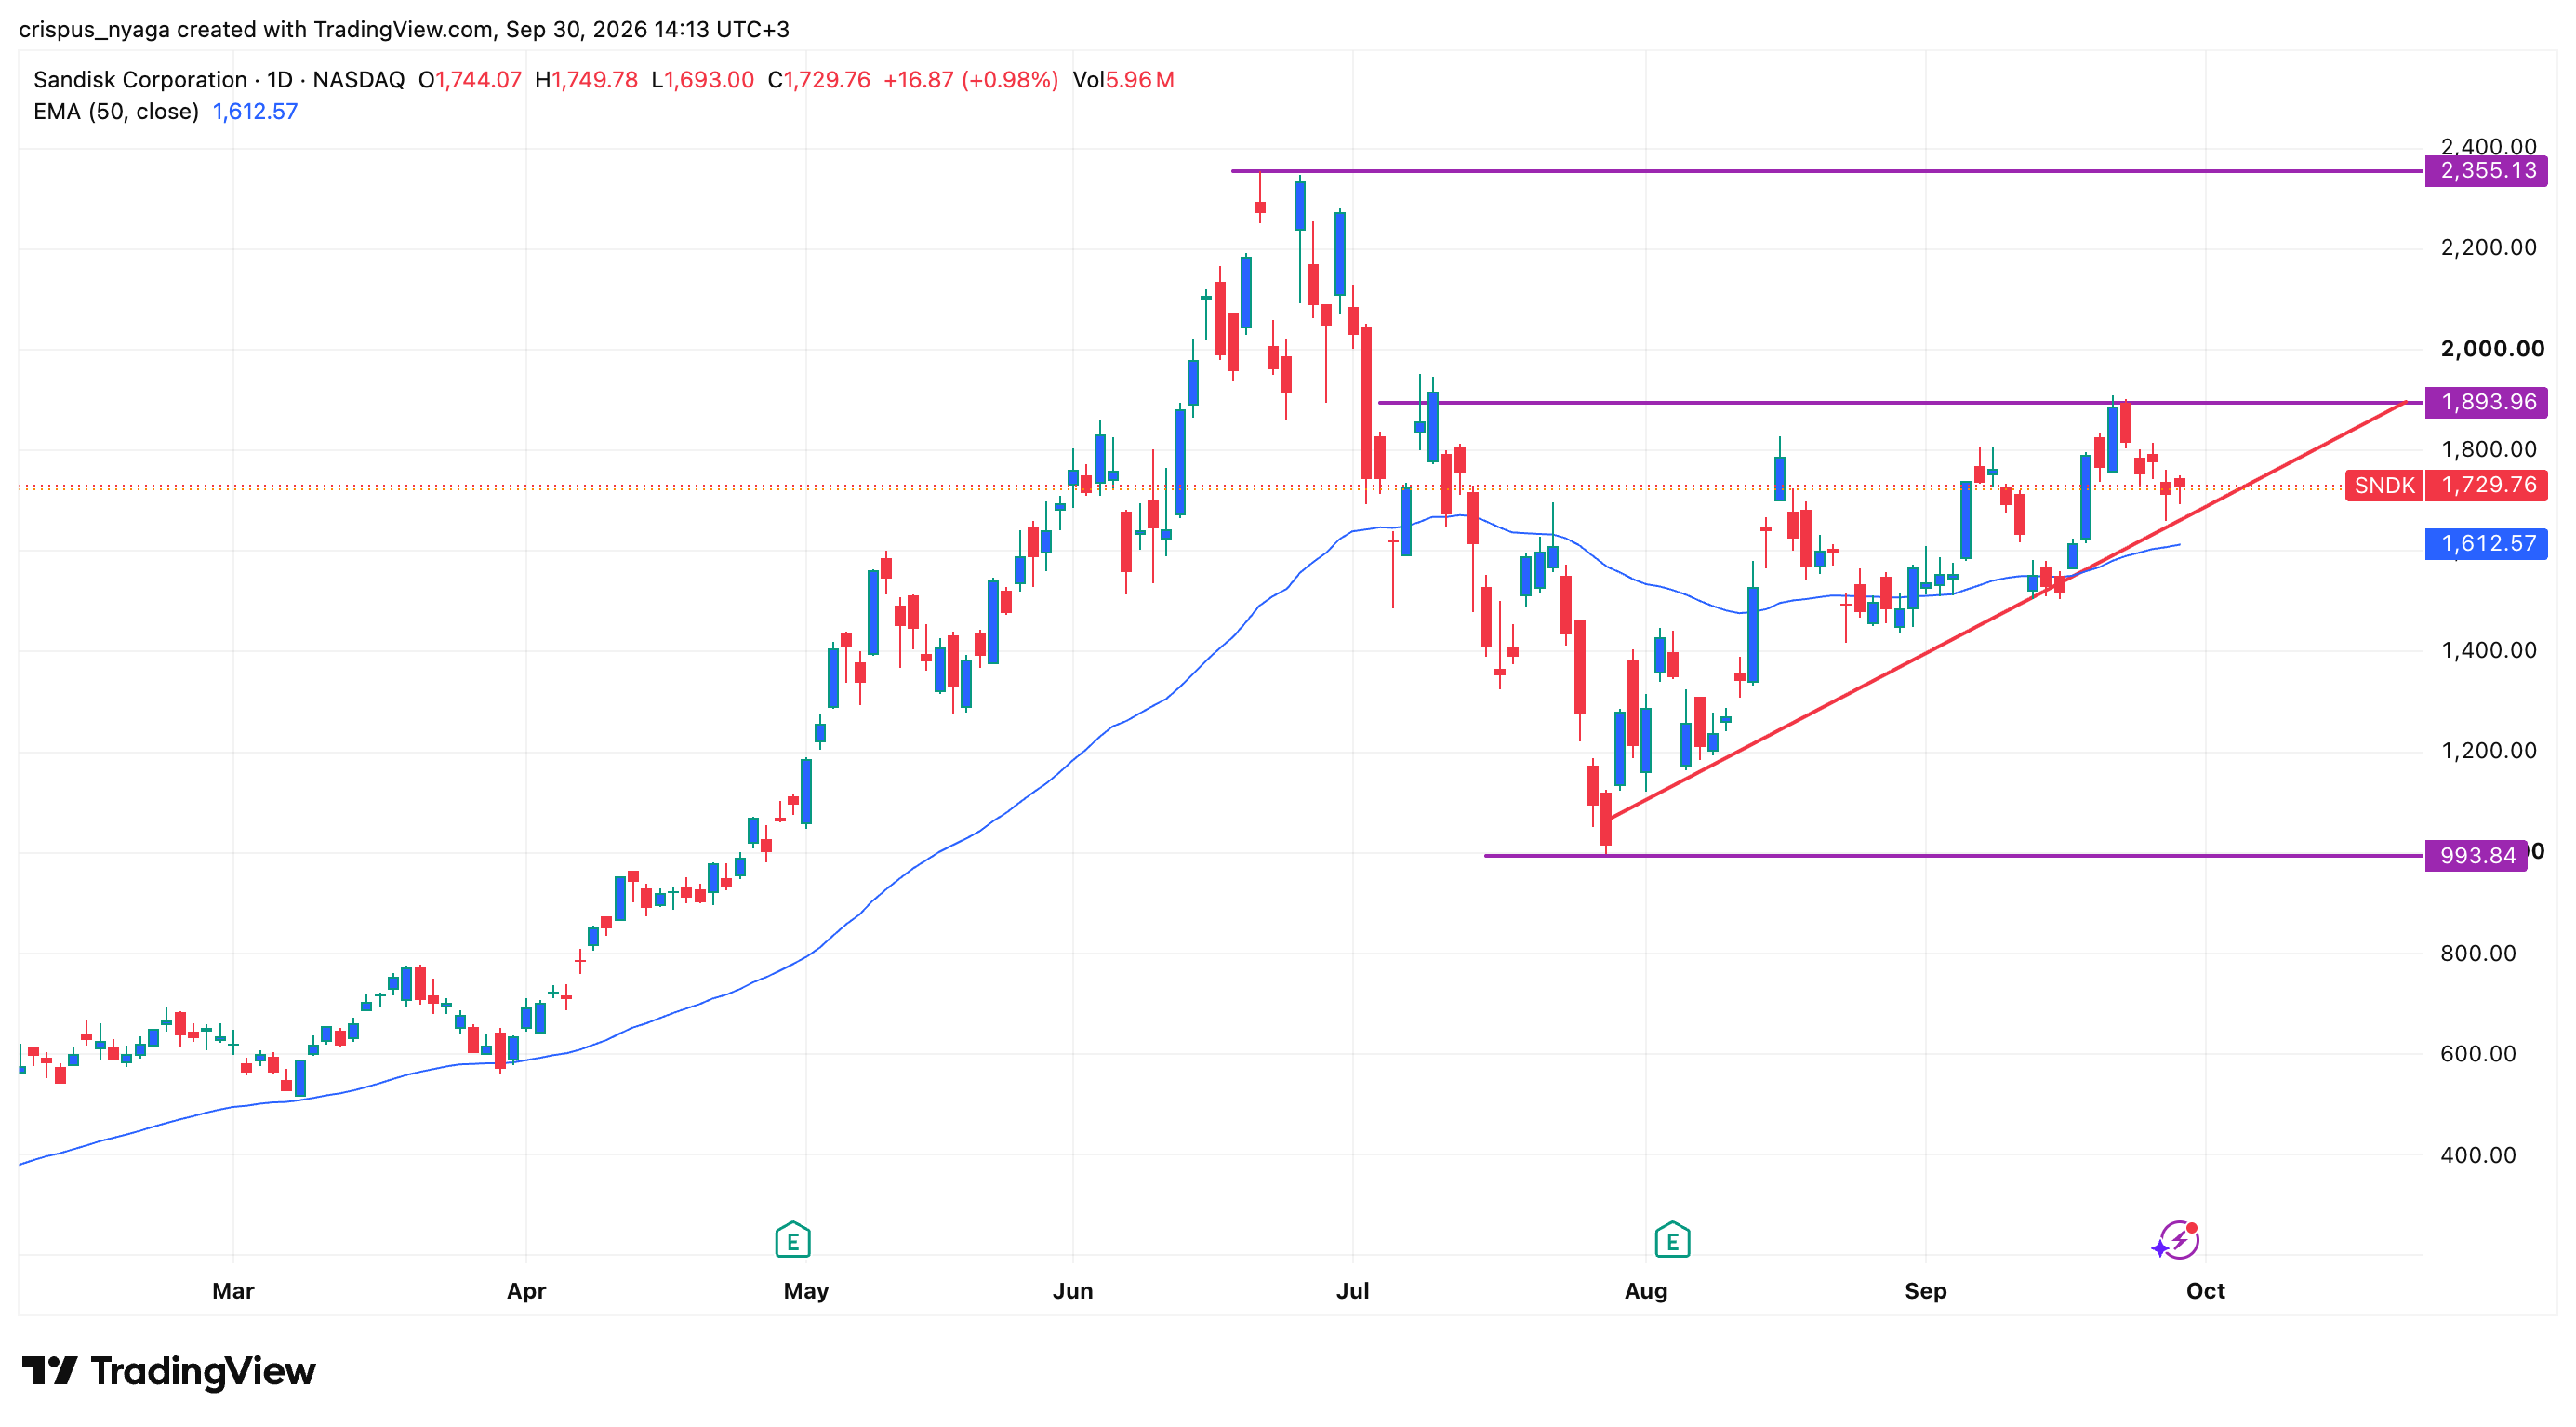
SanDisk stock has traded sideways over the past few weeks as the strong momentum from earlier this year has stalled. SNDK is currently at $1,730, about 8.6% below this month’s high of $1,893. The consolidation has formed an ascending triangle, a pattern that often precedes an upside breakout, so a strong rebound is possible if buyers push the price above resistance.
SanDisk stock has formed a highly bullish chart pattern
The daily chart shows that SNDK stock peaked at $2,355 in June and then pulled back to $993 in July. Since then, the stock rebounded and hit a major wall at $1,893, forming an ascending triangle pattern. This pattern normally leads to a bullish breakout, which happens when the two lines are about to converge.
In this case, the pattern height is about $900, which is estimated by subtracting its lower price and the upper side. By adding this price with the upper side of the triangle, we can estimate the potential target to $2,793. This view will be confirmed if it jumps above $2,355, its all-time high.
The other bullish catalysts for the stock are the fact that it has remained above all moving averages and the Supertrend indicator.
SanDisk’s business is doing well
The main catalyst for the stock is the ongoing revenue and profitability growth. Its last financial results showed that its revenue growth gained momentum, with the revenue soaring by 372% YoY to $8.9 billion. This growth was driven by a 1,298% increase in its data center revenue and a 392% jump in its edge business.
The management also boosted its forward guidance, citing the ongoing demand for its products and its large deals with some of the biggest companies in the United States.
Analysts expect the upcoming earnings report to show that its revenue jumped by 362% to $10.68 billion. After this, revenue is expected to jump by 304% in the next quarter to $12.2 billion, bringing the annual revenue to $48 billion, followed by $58 billion.
SanDisk’s profits are expected to surge, with the quarterly earnings-per-share rising from $1.22 to $46.18. Its annual EPS is expected to surge from $70 to $213 this year.
In addition to all this, the company is highly undervalued, with the forward price-to-earnings ratio being 8, much lower than the technology sector median of 23.20. This multiple is also much lower than other similar companies, including top names like Micron, Kioxia, and Samsung Electronics.
Analysts maintain a highly bullish outlook for the company, with Cantor Fitzgerald seeing it rising to $2,900. Wedbush analysts expect the stock rising to $2,000, while Mizuho sees it rising to $1,875.
Additionally, Rosenblatt’s Kevin Cassidy hiked his target to $2,400. These analysts note that the company’s business continues to do well and that its long-term contracts with top customers. These contracts have set a floor and a ceiling price for its chips, shielding it from the boom and burst cycles in the memory industry.